
Back to the woodpile · Thematic · 15 Oct 2026
Back to the woodpile
HIGHLIGHTS
Europe goes into winter with less gas in storage than at any point in the past 15 years. EU storage was at 70.9% of capacity full on 26 September, against a 90% full target for 1 November, and Germany is one of the least protected at just 57% full. The cause is the closure of the Strait of Hormuz to LNG shipments. Shell estimates that 36 million tonnes a year of Qatari and UAE supply has been removed, putting North Asian buyers in direct competition with Europe. Asian spot LNG has nearly tripled to about $30/MMBtu, and industry executives at Shell, Cheniere and Wood Mackenzie have warned of further spikes if the winter is cold.
The argument is strongest for three groups of households: those heating with oil or LPG, those using direct electric heating, and rural homes with a chimney and access to logs. It is weakest for urban homes on mains gas in the UK, where the price cap delays and softens the signal. The best-placed listed names are wood-fuel suppliers and stove makers whose results are dominated by wood heat: Poujoulat, Cogra 48 and Tulikivi, with NIBE as the large, liquid way in. UK stove sales rose 40% in 2022, NIBE Stoves grew 31.5% and Poujoulat’s wood-energy sales rose 57.8%. The most wood-exposed stocks rose 44–106% at their best within a year.
Delivered heat from logs costs about a third of gas in France. Pellets are about 20% cheaper than gas in Germany, and logs and pellets are roughly 17–70% cheaper than heating oil in every market we looked at. Kiln-dried logs beat mains gas once the cap gas rate passes 9.66p per kWh. Cornwall Insight forecasts 9.76p for January–March 2027, up from 7.97p today.
Our thesis is that a second European gas shock in four years will drive a fresh jump in demand for wood-burning stoves, pellet stoves and wood fuel. The 2022 Euro energy crisis caused by the Russian invasion of Ukraine shows the size of the response. UK stove sales rose 40% in 2022, NIBE Stoves grew 31.5% and Poujoulat’s wood-energy sales rose 57.8%. The most wood-exposed stocks rose 44–106% at their best within a year.
01Europe's impending energy crisis+
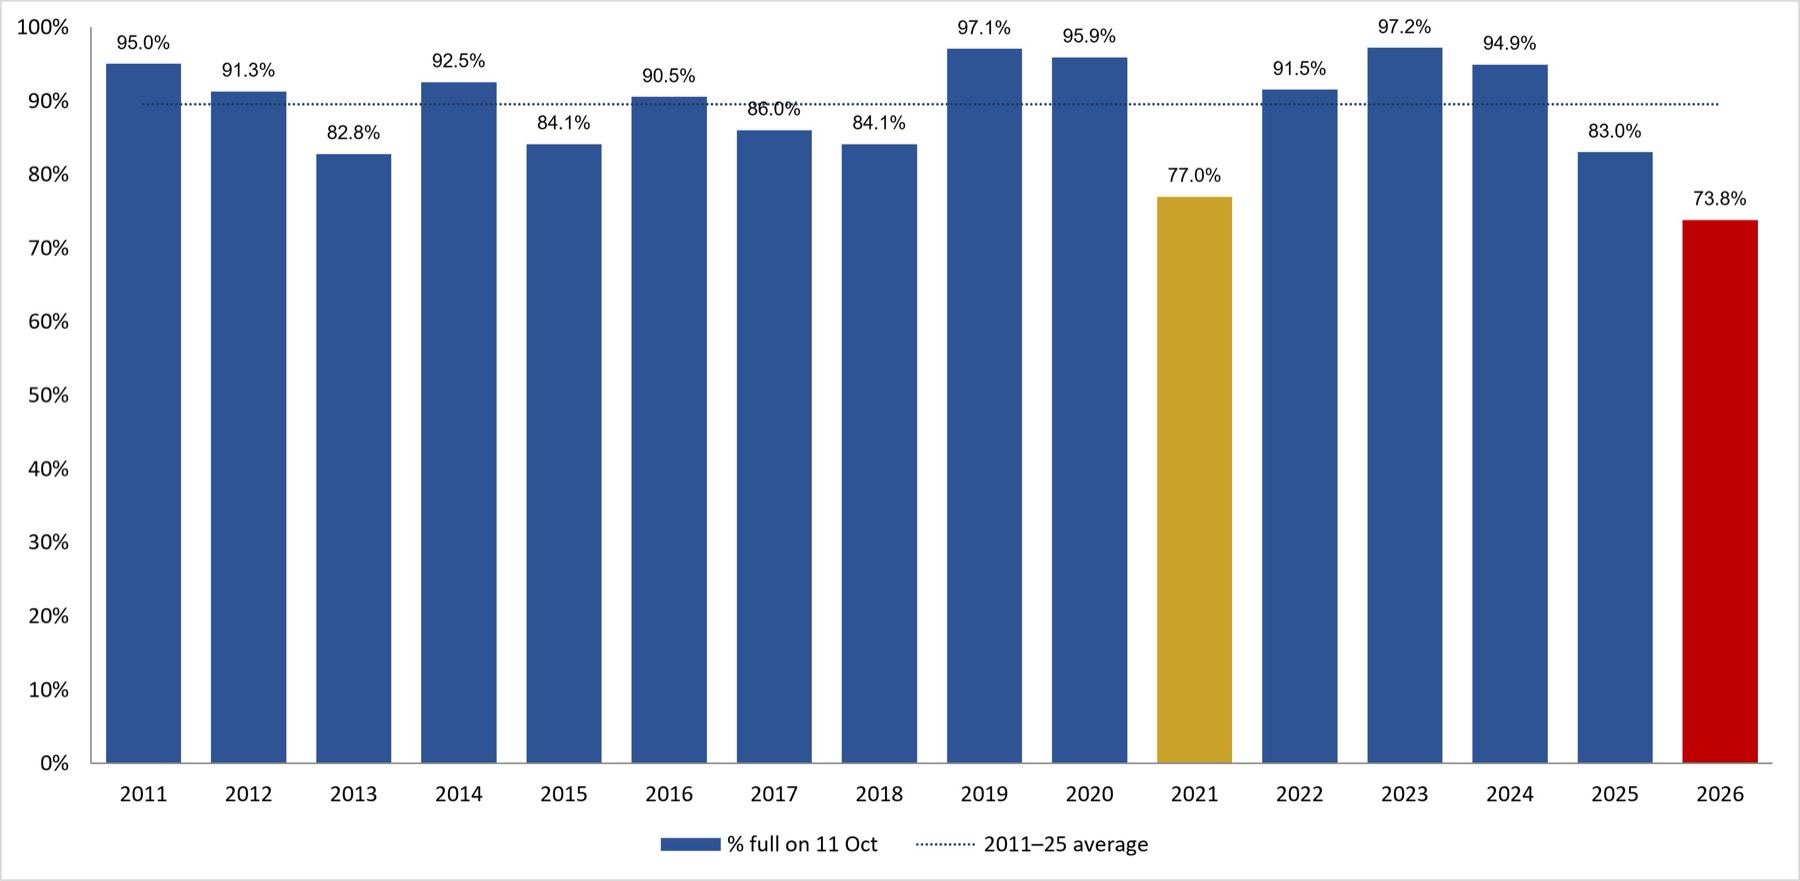
Europe goes into winter with less gas in storage than at any point in the past fifteen years. EU storage was 70.87% full on 26 September 2026, against a 90% target for 1 November. We note that the EU has already relaxed this target so a member state only needs to reach 90% full at some point between 1 Oct and 1 Dec. Germany, the largest market for wood stoves and pellets, was at 57%, and the Netherlands at 56.5%. Analysts at CES Intelligence expect the EU to finish the injection season at 74–78%.
The cause is the closure of the Strait of Hormuz to LNG shipments. Shell estimates that 36 million tonnes a year of Qatari and UAE supply has been removed, putting North Asian buyers in direct competition with Europe. Asian spot LNG has nearly tripled to about $30/MMBtu, and industry executives at Shell, Cheniere and Wood Mackenzie have warned of further spikes if the winter is cold.
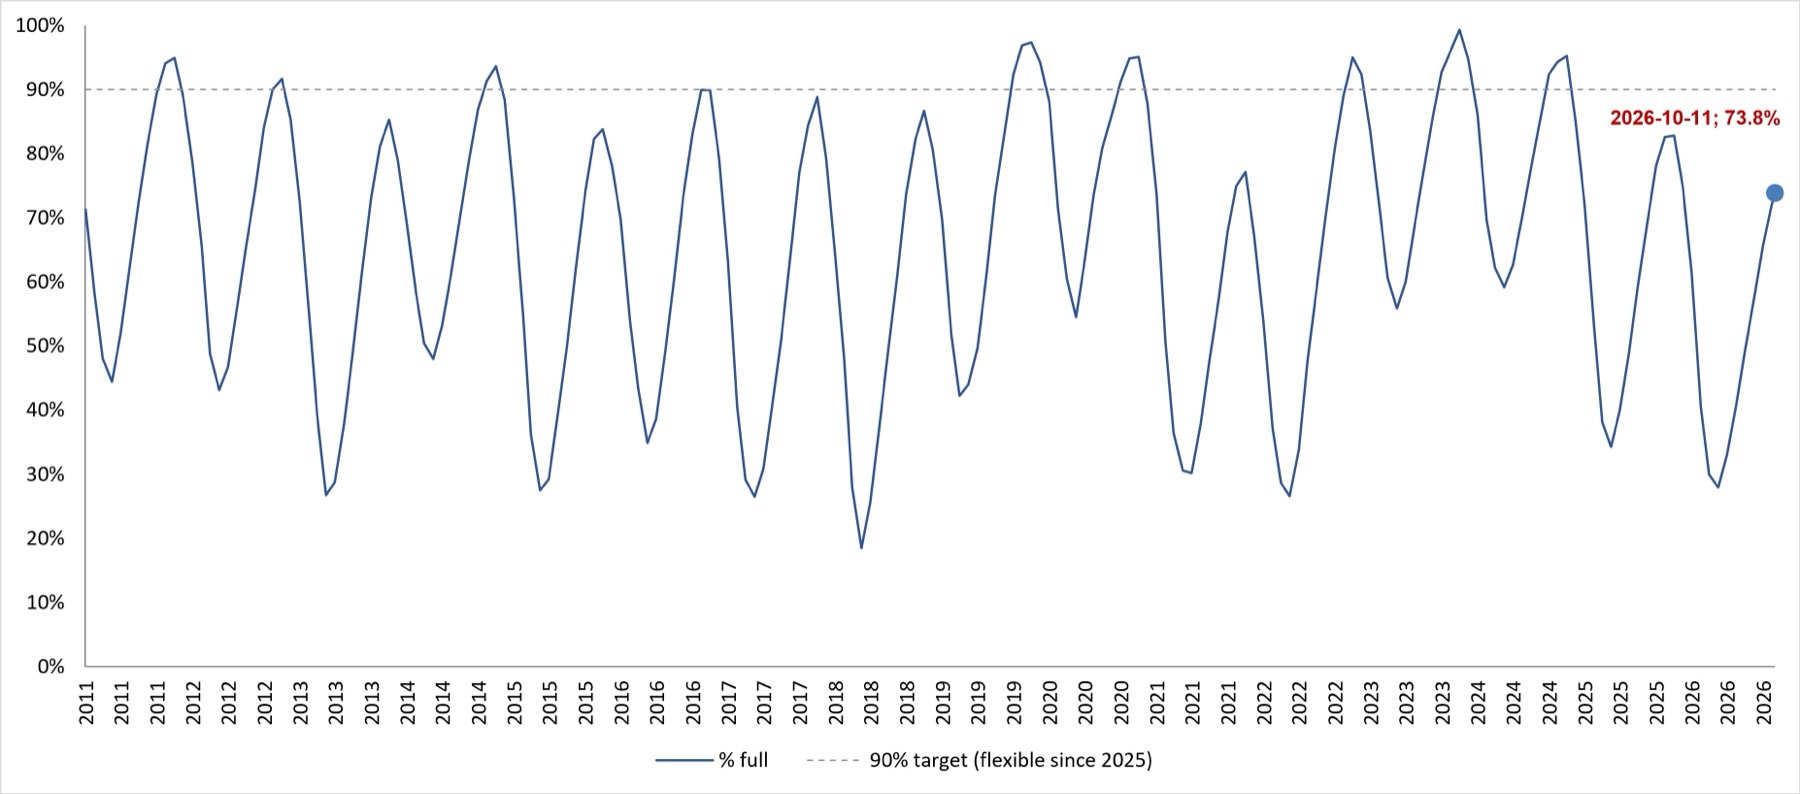
The official EU target is that existing storage across the EU-27 should be 90% full ahead of winter, but recently the EU has become much more flexible than the original crisis rule.
Timing: each Member State is meant to reach 90% full at any point between 1 October and 1 December. Once a member reaches that target it does not have to stay there. The original 2022 rule required 90% by 1 November.
Levels: There are allowed shortfalls: up to 10 percentage points below target in difficult market conditions, for example if speculation makes filling uneconomic; a further 5 points for countries whose own production exceeds their consumption, or that have large, slow-injecting storage sites; up to 5 more points for one season, if the Commission adopts a delegated act because poor market conditions persist.
Interim targets: each country sets its own filling path for February, May, July and September, based on its previous five years. There are no fixed EU-wide interim targets.
Scope: the target applies to each Member State, not to the EU total.
What it means for this upcoming winter: EU storage was 73.8% full on 11 October. With the standard 10-point allowance the effective floor is 80%, and it could fall towards 75% if the Commission widens it. Storage rose only about 2 points in the first 11 days of October, and November normally brings net withdrawals. So many countries look likely to use the allowances rather than reach 90%.
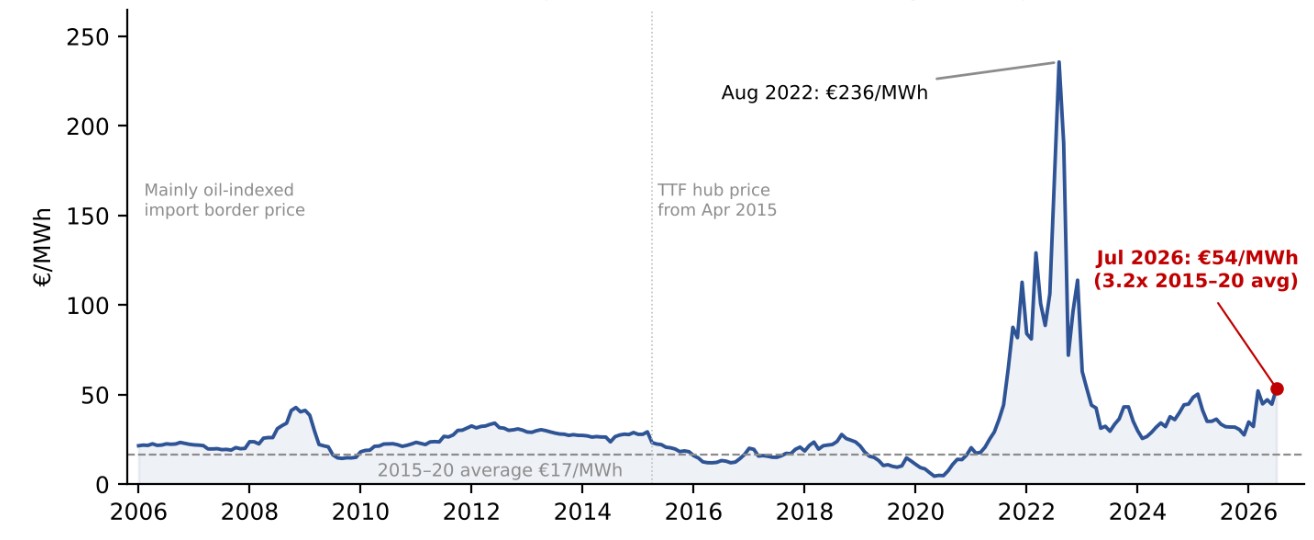
This is already reaching household bills. Ofgem raised the UK cap by 4% from 1 October and named higher wholesale gas prices caused by the Middle East conflict as the reason. On 30 September Cornwall Insight forecast a further 16% rise for January–March 2027, to £1,999 a year for a typical household, with the gas unit rate rising to 9.76p per kWh. Ofgem’s observation window means September’s wholesale rise is already locked in.
Policy adds a slower, structural push. The EU’s second emissions trading system (ETS2), which puts a carbon price on heating fuels used in buildings, was postponed from 2027 to 2028 in December 2025. Each €50 per tonne of CO₂ adds roughly 1 cent per kWh to gas and about 13 cents per litre to heating oil. Under EU ETS rules biomass carries a zero emission factor, so wood should be largely outside this cost
Investors should note that ETS version 2 will widen the cost gap in wood’s favour from 2028. Gas and heating oil will carry a carbon cost and wood won’t. In the early years the price is managed at about €45/tonne in 2020 money, which adds roughly 0.8 c/kWh to household gas and 1.2 c/kWh to heating oil. That is also a possible structural tailwind for wood heat.
02Is wood cheaper than oil, gas, and electricity?+
Due to significant rises in gas and oil prices over the last 6 months, wood is now one of the cheapest ways to heat a home in most of Europe. The fair comparison is the cost of a KWh of heat delivered to the home, after adjusting for the efficiency of each type of appliance. On this basis wood beats heating oil and direct electric heating in most markets. It beats gas clearly in France and Germany, and it is close to break-even in the UK, where the government imposed price cap has held gas prices down.
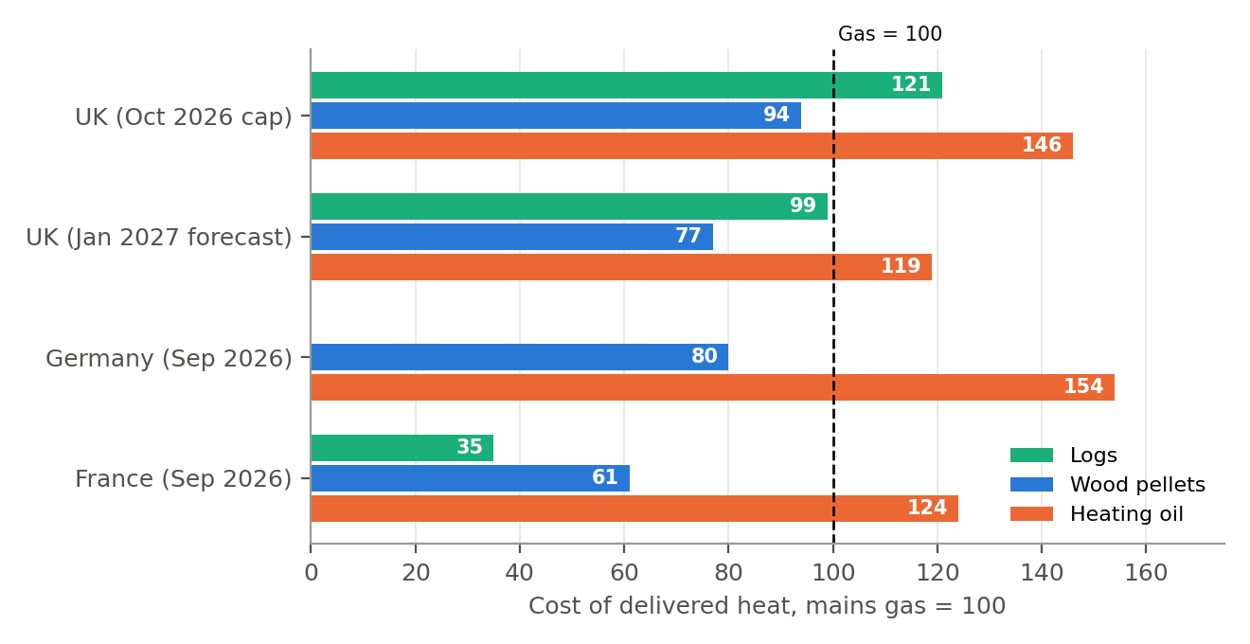
In the UK gas is currently cheaper than wood on a per KWh basis At the October price cap, mains gas costs about 8.9p per kWh of delivered heat, and kiln-dried logs in a modern stove about 10.7p. Bulk-blown pellets already undercut gas at 8.3p. Heating oil has risen sharply with crude: at 114p a litre it costs about 13.0p per kWh of heat, so logs are now about 17% cheaper than oil. However if wood prices remain stable then we expect wood to be cheaper than gas in Jan 2027 when the government cap on gas prices will rise. Cornwall Insight’s January forecast of 9.76p takes the cap just past that point (Figure 4). For the 22 million households on the cap the switch is marginal, but a household that drops gas entirely also saves the gas standing charge of about £108 a year. For the roughly 1.5 million UK homes heated by oil, wood is already clearly cheaper
| Heating option | Fuel price | Delivered heat, p/kWh | vs gas at Oct cap |
|---|---|---|---|
| Mains gas, Oct–Dec 2026 cap | 7.97p/kWh | 8.86 | 100 |
| Mains gas, Jan–Mar 2027 forecast | 9.76p/kWh | 10.84 | 122 |
| Wood pellets, bulk blown | 35.9p/kg | 8.31 | 94 |
| Air source heat pump | 26.32p/kWh | 8.95 | 101 |
| Wood pellets, bagged | 43.9p/kg | 10.16 | 115 |
| Kiln-dried logs, modern stove | 37.3p/kg | 10.73 | 121 |
| Heating oil (kerosene) | 114p/litre | 12.95 | 146 |
| Direct electric heating | 26.32p/kWh | 26.32 | 297 |
Germany is the largest pellet market and the most exposed to the gas shortfall. The German pellet association’s index (DEPI) was €454.21 a tonne in September 2026, or 9.1 cents per kWh. On DEPI’s own comparison, pellets are about 20% cheaper than natural gas and about 48% cheaper than heating oil. Heating oil cost €162.77 per 100 litres on 5 October, and Verivox puts the average new-customer gas tariff at about 13 cents per kWh, up from the 9.6 cents the Bundesnetzagentur modelled for January 2026
France gives the clearest result. Logs in a modern stove cost about 6.0 cents per kWh of delivered heat, against 17.0 cents for gas in a condensing boiler, 20.0 cents for direct electric heating and 21.1 cents for heating oil. Pellets cost about 10.2–10.4 cents. Only heat pumps (5.7–7.4 cents) compete with logs, and they need far larger upfront spending. The wood price is an ADEME-based estimate rather than a market survey, so we treat it as indicative.
Wood prices are not fixed. The German pellet index has risen about 36% in a year and 6.2% in September alone, mainly because sawmills are cutting less timber, which reduces the residues used to make pellets. In 2022 the index peaked at €763.76 a tonne in September, eroding much of the advantage over gas just as demand peaked. Logs are less exposed: they are traded locally, often seasoned on site, and in rural areas frequently self-supplied.
| Country | Wood for space heating | Share of national space heating |
|---|---|---|
| France | 251 PJ | 24% |
| Germany | 207 PJ | 14% |
| Italy | 196 PJ | 27% |
| Poland | 164 PJ | 32% |
| Romania | 105 PJ | 54% |
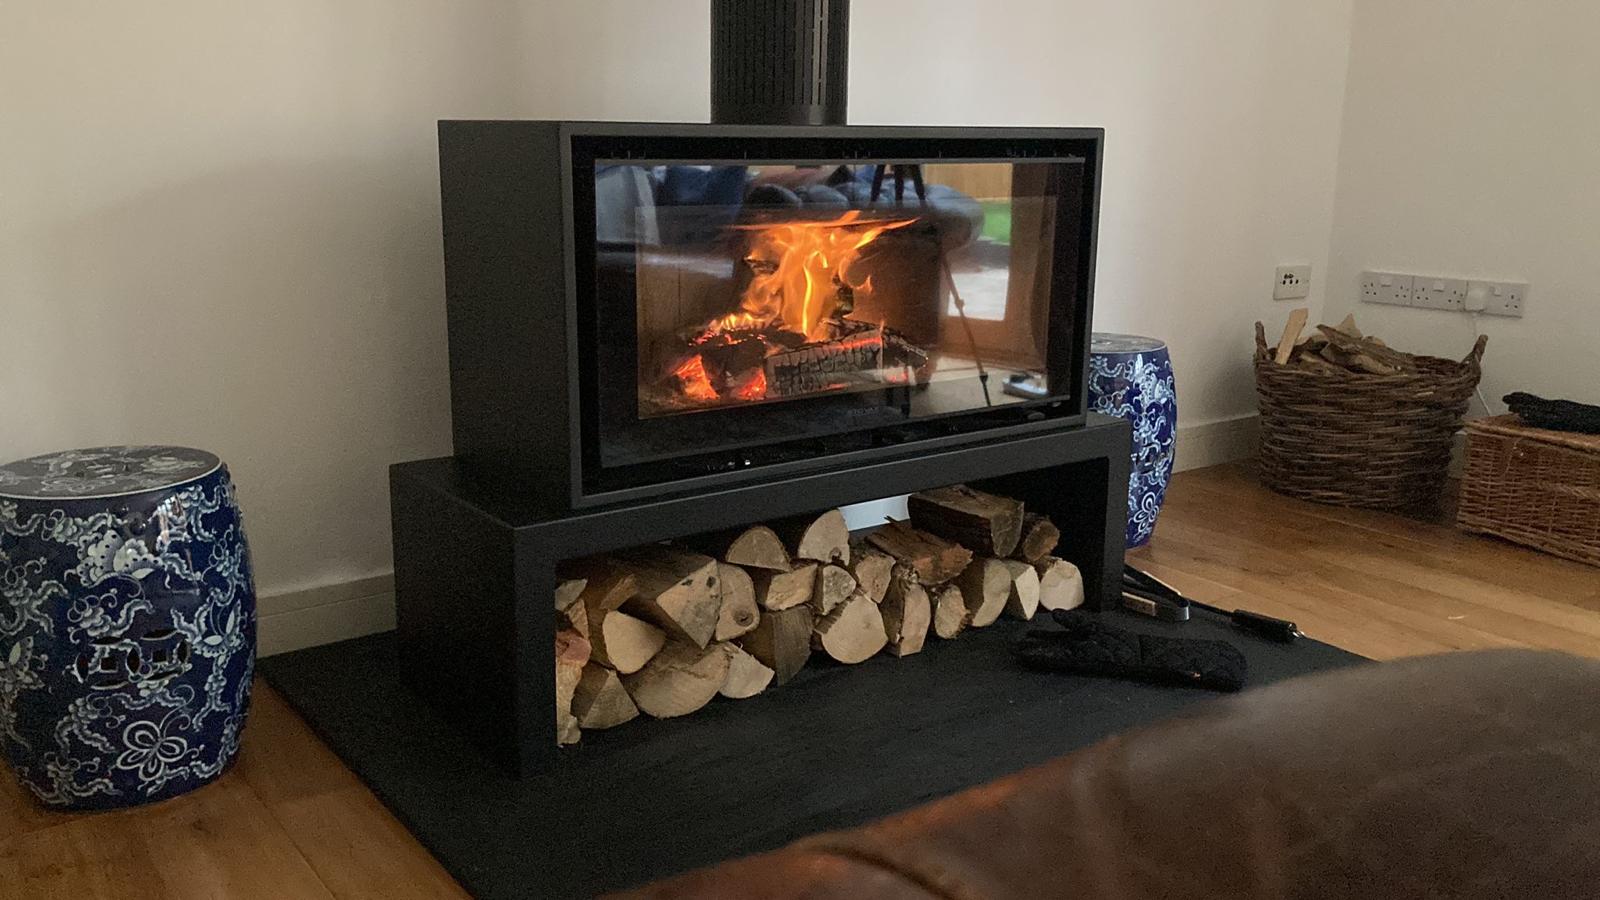
This analyst has run the numbers in terms of his own home. A Stovax Studio Air 2 that is rated at 8.2 KW with a stated 78.5% thermal efficiency v's a condensing natural gas boiler and underfloor heating with 90% efficiency. I mainly burn ash which is a very energy dense wood and gives 4.1KWh per kg and 550 kg per stacked cubic meter, for which I currently pay GBP 130 per stacked cubic meter. Even at today's gas price wood is cheaper and as the gas price rises through the winter I expect those savings to become larger.
| Wood (Stovax Studio Air 2) | Gas (condensing boiler) | |
|---|---|---|
| Energy in fuel | 550 kg × 4.1 kWh/kg = 2,255 kWh per m³ | 1 kWh per kWh |
| Efficiency | 78.5% | approx 90% |
| Useful heat | ~1,770 kWh per m³ | 0.90 kWh per kWh |
| Cost per kWh of useful heat | 7.3p | 8.7p |
Is it possible to burn wood to heat your home and still care about the environment? We think it is - and to some extent the EU seems to agree with us. Specifically the EU Emissions Trading Scheme rules state that biomass carries a zero emission factor presumably because wood is not a fossil fuel, it is biogenic CO₂ that is accounted for in land-use emissions rather than at combustion. In addition we understand that EU law classes biomass as a renewable fuel.
Burning wood releases carbon dioxide: roughly 1.8 kg for every kilogram of dry wood. Yet wood heat is widely treated as renewable energy. The reason is that trees absorb carbon dioxide as they grow and release it again when they die, whether they are burned or left to rot. Burning simply releases that carbon faster. Provided the wood comes from forests that are replanted and managed so that regrowth keeps pace with harvesting, the carbon cycle stays broadly in balance.
Forests are able to absorb an extraordinary amount of carbon dioxide. The problem is that trees don't live forever. Sooner or later the tree dies and starts to decay. The same gases are then released in the same quantities as they would if they had been burnt. Thus, heating with wood does not lead to an increase in greenhouse gases, providing that consumption and renewal are balanced on a global scale.
What burning wood does do is increase non CO2 pollution such as small particulates (PM2.5) and these can have a detrimental impact on human health. The EU has regulation in place such as the Ecodesign rules for solid-fuel local space heaters (Regulation (EU) 2015/1185) which have applied since January 2022. It sets limits on PM, VOCs, CO and NOx for new stoves. In addition local markets have their own rules such as Germany emissions ordinance (BImSchV), whose final deadline forced old stoves to be replaced or retrofitted. Some French areas and Dutch municipalities restrict burning locally, for example on windless days.
03History is our guide - What happened last time?+
The 2022 EU energy crisis that flowed from the start of the Russia Ukraine conflict is perhaps the most recent example of how wood heat responds to a gas price shock. We screened over 100 listed companies that are leveraged to the theme of burning wood to heat homes. These include manufactures and sellers of wood burning stoves, companies that supply wood and other wood products for burning such as pellets etc, and companies that provide tools for handling fire wood such as chainsaws and axes. We looked at their share price performance over the period of the last large energy crisis in Europe and found the following
- Only the companies that are mostly in manufacture of wood heaters outperformed. Tulikivi (TULAV: HE) rose 106% at its best, Cogra 48 (ALCOG: PA) 85%, Poujoulat (ALPJT: PA) 77%, EO2 (ALEO2: PA) 63%, NIBE (NIBE B: ST) 63% and Moulinvest (ALMOU: PA) 44%. for comparison the STOXX Europe 600 rose 2.5%.
- All of them gave the gains back. Poujoulat is 83% below its best close, Cogra 65%, EO2 62% and NIBE 64%. Only Tulikivi still trades above its pre-Ukraine invasion price.
- The adjacent plays moved much less. Most tool makers, DIY chains, LPG distributors and insulation makers were flat or down. A few rose 25% to 45% at their best, among them NWF (UK heating oil), Andritz (pellet mills), Drax and SCA (pellets). Home batteries rose most: Pylontech 212% and SMA Solar 211%.
- Many European wood stove makers are private and family-owned. NIBE has bought about fifteen stove brands, and Jøtul has been owned by its bondholders since April 2025.
For specific stocks we observed the following
- UK stoves: Stove Industry Association (SIA) members (who represent almost 70% of the manufactures) reportedly sold more than 35,000 stoves in Q2 2022, about 40% more than a year earlier. Full-year 2022 sales rose 40%, and sales in H1 2023 rose a further 19% to more than 86,300 units.
- NIBE Stoves: sales rose 31.5% in 2022 (26.1% excluding acquisitions), with an operating margin of 13.7%.
- Tulikivi: 2022 sales rose 32.1% to €44.3m, the operating margin rose from 8.1% to 10.6%, and the order book nearly tripled to €17.2m.
- Poujoulat: in FY2022/23 group sales rose 33.0% and wood-energy sales (pellets and logs) rose 57.8%.
- Wood fuel: Cogra 48’s sales rose 50% in FY2021/22, EO2’s pellet sales 37%, and Moulinvest’s pellet sales 48.5%. Component maker SIT later reported that pellet-stove applications fell 77.5% in 2023 after benefiting in 2022 from high gas prices, which shows how quickly the cycle turned.
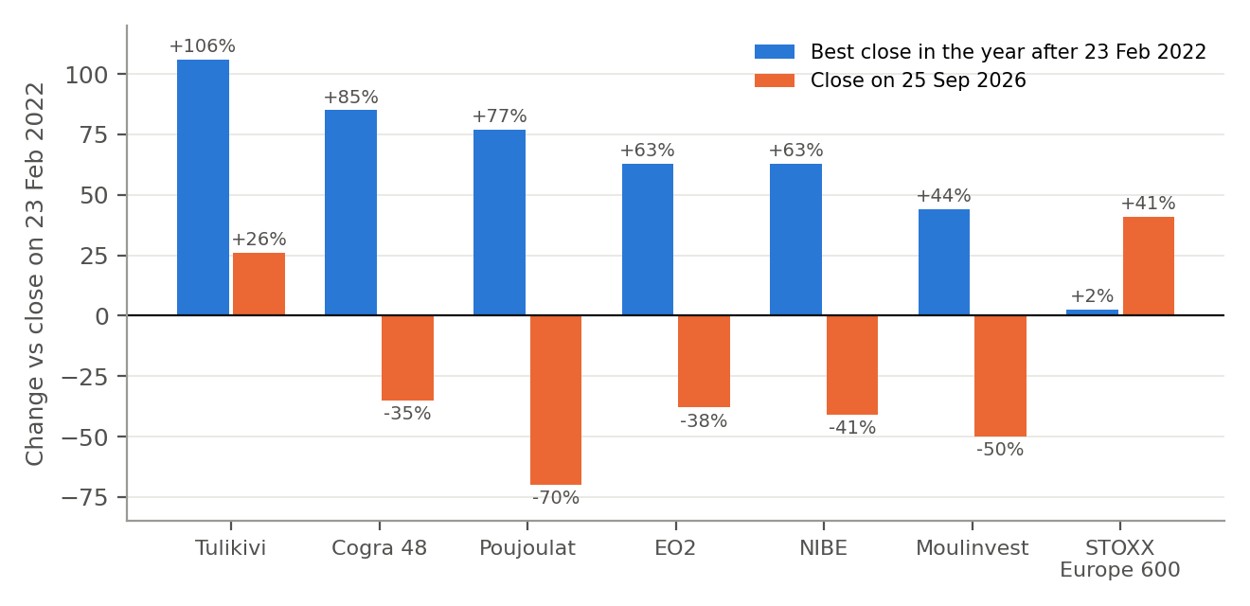
Share prices followed, and then gave it all back. We measured each company from its close on 23 February 2022, the last trading day before the invasion of Ukraine. The most wood-exposed companies rose 44–106% at their best within a year, against 2.5% for the STOXX Europe 600. By 25 September 2026 all but Tulikivi were below their pre-invasion price, while the index was 41% higher.
We draw two lessons.
- The market responds quickly to a gas price shock - in 2022 share prices of listed wood stove and wood supply companies rose quickly and likely ahead of any move in order books - typical of some quick themes
- The gains did not last because demand was pulled forward, pellet prices rose and gas prices fell back. Investors should treat this as a cyclical opportunity with a defined window
Poujoulat has the best mix of leverage and evidence. Wood energy is nearly half of sales, and those sales rose 19.3% in Q1 of FY2026/27, before the heating season. At €41.7m the company is valued at about 0.12 times sales, against a pre-invasion share price more than three times today’s. The Coirier family controls 66.87%.
Cogra 48 is almost entirely pellets and grew 24% in the year to June 2026. It lost €4.7m in FY2024/25, so the recovery is from a low base
Tulikivi is the only listed pure-play maker of wood fireplaces, and the only wood-heat pure play trading above its pre-invasion price. Sales are still falling (H1 2026 −7.5%), so it needs a demand response to come through
EO2 is very small (€6–7m) and loss-making in pellets, with liquidity to match. We include it for completeness.
NIBE is one of the most liquid, large-cap way to own European stoves, with about SEK 300m of shares traded a day. Stoves are only 8.5% of sales and the division is under pressure: H1 2026 sales fell 5.3% and the margin was 0.8%, partly because of US tariffs on Canadian-made stoves (about SEK 150m a year). But NIBE gives two-way exposure to a gas shock. Its Climate Solutions division (heat pumps, two-thirds of sales) grew about 26% excluding acquisitions in 2022. A margin recovery in Stoves from 0.8% back towards its 13.7% 2022 level would add several hundred million kronor to operating profit.
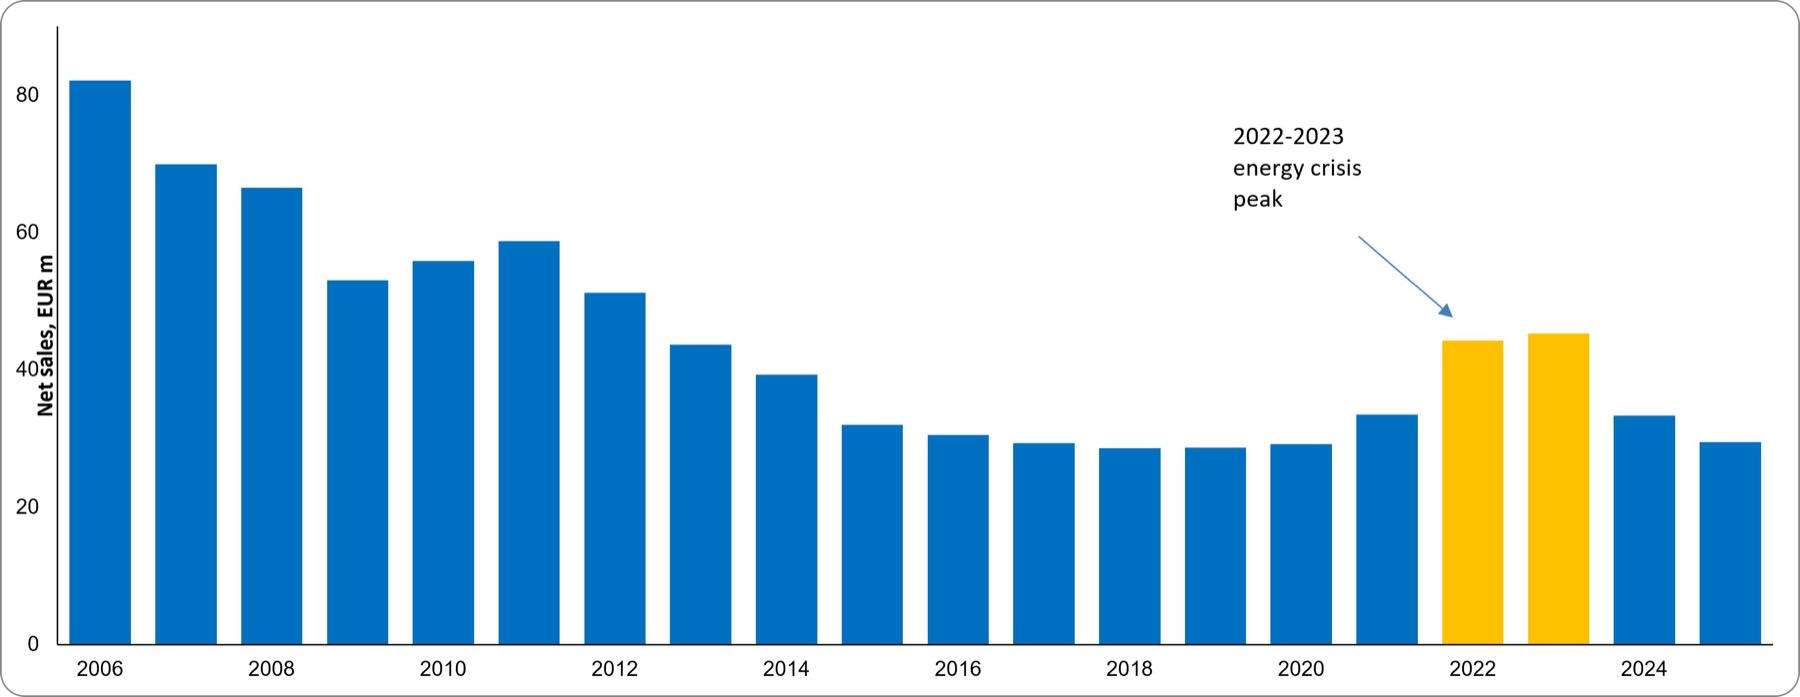
If we take a look at Tulikivi's historic revenue we can clearly see the cyclicality of the demand. As the figure below shows, the 2022 Russia Ukraine event caused a jump in demand for wood burning stoves that had been in decline since the peak of the building boom of 2008-2010. That jump in demand was shortfelt and sales declined after the event
Investors should note that its not just the energy crisis that will drive sales of stoves. What we are arguing is that the energy crisis simply brings forward additional demand.
- Lifestyle. In many markets a wood burning stove is a discretionary/ luxury home-improvement purchase as much as a heating device, which makes demand sensitive to incomes and home building / improvement cycles.
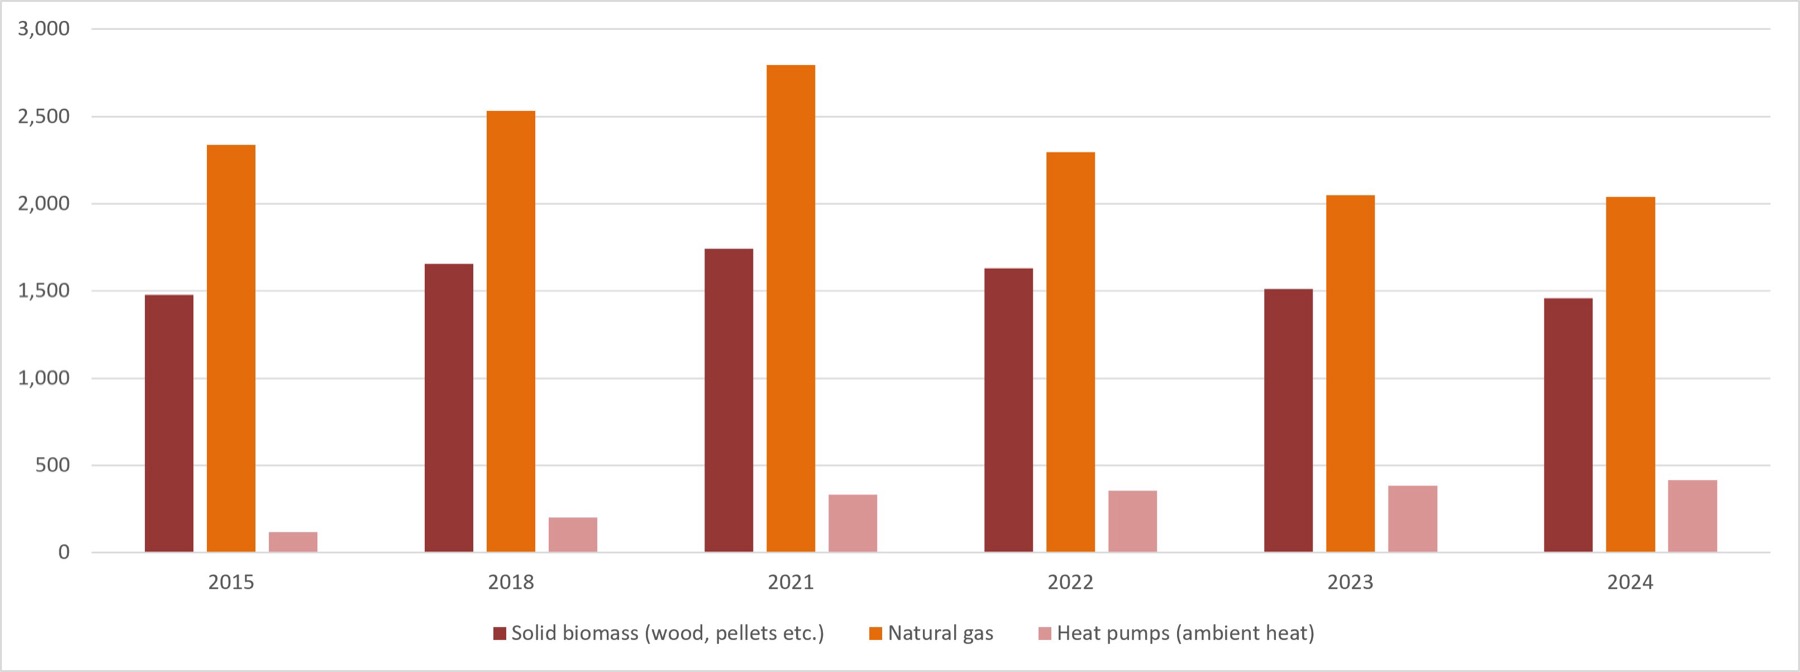
- Competing technologies. Heat pumps have more than tripled their share of EU home heating since 2015. Pellet stoves win where subsidies favour them.
- Environmental Policy risk. Particulate rules in cities, possible wood-burning restrictions (a live debate in the UK and Germany), and building codes that favour heat pumps all weigh on the long-term market.
- Weather. Cold winters lift both wood use and the urge to buy. The milder EU winters of 2023–24 reinforced the slump.
| Driver | Details |
|---|---|
| Replacement demand: the steady base | This is most of the market in normal years. In Germany more than 75% of stoves sold replace an old unit, from an installed base of about 11.5 million (HKI). Regulation forces replacements. Germany’s emissions rules have retired about 2 million old stoves since 2010, with a final deadline at the end of 2024. The EU’s Ecodesign standards and France’s MaPrimeRénov’ subsidies work the same way. Tulikivi benefits, since its stoves already met the tighter limits.Subsidies move it sharply. France’s 2025 log-stove sales fell 23% when MaPrimeRénov’ was cut, while subsidised pellet stoves rose 35%. |
| Housing demand: the structural driver | New homes and major renovations are the natural moment to install, especially for heavy heat-retaining fireplaces that need a chimney and a strong floor. This is Tulikivi’s core Finnish market, so weak building in 2024–26 has hurt it directly. Consumer confidence decides whether renovations happen. Tulikivi’s management cites it every quarter. |
| Energy-security demand: the swing factor | Price spikes and supply fears drive it. It produced 2005–06 and 2022: French sales peaked at about 512,000 units in 2022, UK stove makers reported +40% and German press described a “run” on stoves. In 2022 buyers saw a stove as a backup if gas ran out, not mainly as a way to save money. Fear matters more than the price level. Demand collapsed in 2023 once storage was full, even though gas was still about 2–3 times its pre-crisis price. In 2023–24 sales fell 40–45% in France and Germany, Tulikivi’s sales fell 26%, and wood used for heating also declined (Eurostat). People bought stoves and then didn’t burn much more wood. It pulls demand forward. A boom year is followed by a hangover, because the buyers who would have come later have already bought. |
| Company | Ticker | Mkt cap (€m) | P/E | P/B | ROE | Avg daily turnover (€) |
|---|---|---|---|---|---|---|
| Tulikivi | TULAV FH | 29.1 | n.m. (loss) | 1.88x | –12.5% | ~10,400 |
| Cogra 48 | ALCOG FP | 22.5 | 45.1x | 1.04x | 2.3% | ~9,400 |
| Poujoulat | ALPJT FP | 41.7 | n.m. (loss) | 0.33x | –2.5% | ~19,900 |
| EO2 | ALEO2 FP | 6.0 | n.m. (loss) | 0.32x | –5.9% | ~370 |
| NIBE Industrier | NIBE B SS | 7,862 | 33.5x | 2.74x | 8.5% | ~22.9m |
| Moulinvest | ALMOU FP | 63.9 | 11.7x | 0.85x | 7.8% | ~13,400 |
- Lack of liquidity is a significant issue. Apart from NIBE, these stocks trade €370–20,000 a day. EO2 had no trades at all on half the days in the last three months. Even a €100k position in Tulikivi is roughly 10 days of total market volume.
- Tulikivi is the most expensive of the small caps on book value. It trades at 1.9x book while losing money, compared with 0.3–1.0x for the French names. That premium reflects the 2026 energy backdrop and the talc option.
- NIBE is the most liquid, profitable way to own the theme, but stoves are a small part of NIBE, it is more leveraged to electric heat pumps.
04Where could we be wrong?+
- Gas prices fall back down. A ceasefire or reopening of Hormuz would ease LNG supply, although Cornwall Insight notes that disruption would take months to clear and storage would still need rebuilding.
- Wood prices rise as well driven by increased demand - Pellets are up 36% in a year in Germany. In 2022 they peaked at €763.76 a tonne, and much of the advantage over gas disappeared.
- In the UK gas prices are kept low by the government. wood fires only break even if the January forecast is right. Most UK demand upside depends on displacing oil-heated and all-electric homes.
- Regulation. Wood burning is a large source of fine particulate pollution (43% of PM2.5 in France). The UK government will consult in 2026 on reducing domestic combustion emissions, and the EU is revising its ecodesign rules for local space heaters. Neither currently proposes a ban.
- Consumers and housing. A stove costs thousands of pounds to buy and install. High interest rates and weak housing markets limit discretionary spending, and NIBE’s CEO recently described European stove demand as subdued.
- Timing and liquidity. The 2022 gains reversed within two years. Most of the high-leverage names are micro-caps with very little daily trading and thin or no analyst coverage.
- UKs Ofgem announcement of the January–March 2027 cap (late November) against the 9.66p log break-even.
- Weekly EU and German gas storage (GIE AGSI+) and the TTF price as the injection season ends.
- The monthly German pellet index (DEPI) for signs that wood prices are tracking gas.
- Stove Industry Association sales data and dealer commentary on enquiries and lead times.
- Trading updates from Poujoulat, Cogra 48, Tulikivi and NIBE, especially wood-energy and Stoves sales.
Research signature
| Report | Thematic research |
| Sector | Building products, home heating |
| Coverage | Europe |
| Date | 15 Oct 2026 |
Disclaimers
General disclaimer and remuneration model. European Equity Research Partners, S.L. ("EERP") is an independent equity research firm domiciled in Spain. EERP is not an investment firm and is not authorised or supervised by the CNMV or by any other competent authority. It produces investment recommendations under the rules applicable to such recommendations in the European Union, namely Regulation (EU) No 596/2014 (MAR) and Commission Delegated Regulation (EU) 2016/958, and under its own Code of Conduct and Conflicts of Interest Policy, available at www.europeanequityresearch.com. This report is thematic, non-sponsored research. It has been prepared at EERP's own initiative and covers a theme across several companies. EERP is not party to any agreement with any company discussed in this report relating to its production, and has not received and will not receive any fee or other consideration, directly or indirectly, from any of those companies or from any third party for its preparation or publication. This report is not "issuer-sponsored research" within the meaning of Article 24(3b) of Directive 2014/65/EU and Commission Delegated Regulation (EU) 2026/1092. EERP does not accept payment in securities, options or warrants.
Companies discussed in this report. EERP provides issuer-sponsored research to listed companies. Companies discussed in this report may be, or may in future become, clients of EERP. Where a company discussed in this report was party to an issuer-sponsored research agreement with EERP in the preceding 12 months, that relationship is disclosed on its company page. The views, ratings and target prices in this report were determined independently of any such relationship.
Accuracy of content. All information used in this report has been compiled from publicly available sources that EERP believes to be reliable; however, its accuracy and completeness are not guaranteed and the information has not been independently verified. The opinions expressed are those of EERP's research department as at the date of publication. Forward-looking estimates and statements are based on assumptions and forecasts of future results and involve risks and uncertainties, so that actual results may differ materially from current expectations.
Exclusion of liability. To the fullest extent permitted by applicable law, and save in cases of wilful misconduct or gross negligence, EERP shall not be liable for any direct, indirect or consequential losses, loss of profits, damages, costs or expenses arising out of or in connection with the access to, use of or reliance on the information contained in this report.
No personalised advice. This report is for information purposes only and does not constitute investment advice or a personalised recommendation for any investor, nor an offer or solicitation to buy or sell securities. The value of investments may go down as well as up and past performance is no guarantee of future results. The securities mentioned may not be eligible for sale in all jurisdictions or to certain categories of investors.
Conflicts of interest and proprietary dealing. EERP maintains a restrictive policy on personal account dealing and conflicts of interest. EERP does not conduct investment business on its own account and does not hold proprietary positions in the securities under coverage. Its directors, employees and contractors may hold positions in those securities or in related securities, subject to EERP's internal policies. Full conflicts-of-interest disclosures and the applicable methodology are available at www.europeanequityresearch.com.
Independence of the research. The views, ratings and target prices in this report are solely those of EERP. They have not been negotiated with, approved or amended by any company discussed in this report, and no draft of this report was disclosed to any of those companies prior to publication. This report is directed at institutional and professional investors. Distribution in the following jurisdictions is subject to the conditions set out below.
Regulatory information. Rating definition. Where this report gives a rating on a company, BUY means an expected total return of +15 % or more over a 12-month horizon; HOLD, an expected total return between -15 % and +15 %; SELL, an expected total return of -15 % or less. Ratings and views are subject to market, macroeconomic, regulatory and company-specific risks, including those set out in this report. Prices and dates. Share prices and market data are as at the close of 15 October 2026 on each company's exchange of listing, unless stated otherwise. Production of this report was completed on 15 October 2026 at 20:33 CET and it was first disseminated on 15 October 2026 at 20:33 CET. Update policy. EERP may revisit the theme and the companies discussed following material events; there is no fixed update frequency. Distribution of recommendations. As at 15 October 2026, EERP's recommendations were: BUY 50 %, HOLD 50 %, SELL 0 %. Of the issuers covered, 50 % were party to an issuer-sponsored research agreement with EERP in the preceding 12 months. Sources. The sources used are listed in the Sources section of this report. Analyst. The lead analyst certifies that the views expressed accurately reflect his personal views on the theme and on the companies discussed and that no part of his remuneration was, is or will be related to the specific views or recommendations in this report. The lead analyst does not hold any position in the securities of the companies discussed or in related financial instruments.
Distribution restrictions. This report has been prepared under European Union law and is directed at institutional and professional investors within the European Union. It has not been prepared in accordance with the laws of any other jurisdiction, and EERP is not authorised or registered outside the European Union. Accordingly, this report is not prepared for, and is not for distribution to or use by, any person or entity in any jurisdiction where such distribution, publication or use would be contrary to local law or regulation, or would require any registration or authorisation that EERP does not hold — in particular the United States, the United Kingdom and Australia, among other jurisdictions. It is the responsibility of each recipient to inform themselves of, and to observe, any such restrictions.
www.europeanequityresearch.com · Copyright 2026 European Equity Research Partners, S.L. (EERP).